
Thomas Triska (Vossloh): Is Vossloh on track to outgrow expectations?

- Thomas Triska said Vossloh had an order intake of roughly one billion after nine months of 2022, a record.
- Vossloh invested roughly 40 million in its factory of the future in Werdohl, where it employs 350 people (2023).
- Sales went from 1.3 billion to around 850 million after the exit from rolling stock, he said (2023).
- In Chinese high-speed rail, Vossloh has had a market share of around 20% for many years (2023).
- The goal is an EBIT margin of at least 10% in all three divisions within two to three years (2023).
Vossloh (VOS)
voestalpine (VOE)
Siemens (SIE) · Alstom (ALO) · Bombardier · CRRC (1766)
What does Vossloh make and how do rail systems differ?
TL;DR: Vossloh employs 350 people in Werdohl, invested roughly 40 million in a new factory and works on a new tension clamp generation (2023).
 Tilman Versch [00:00:00] To transition the world to a cleaner state and to a net zero carbon world, a lot of investment is done and train infrastructure in this case is a very interesting place to look at. So I’m very happy to welcome Vossloh to this episode of Good Investing Talks. They are maybe a kind of boring company, but they’ve transitioned over the last years to an interesting pure play into the mobility and training space. I hope you enjoy my conversation with the company.
Tilman Versch [00:01:07] Dear audience of Good Investing Talks, it’s great to have you back on the podcast. Today, I’m talking with Mr Triska of Vossloh and Vossloh is located in Werdohl. There’s Werdohl on the map.
Among the top three employers, with 350 people in Werdohl
Tilman Versch [00:01:37] What kind of importance do you have for this region?
The US is mostly freight, Europe both passengers and freight
Tilman Versch [00:02:23] Many of my viewers are coming from the US, so if you compare the US railway system and the European railway system, how are they different? So you’re doing business in both markets. So you maybe have the chance to do a comparison of both markets?
Different forces, with extra components for high speed
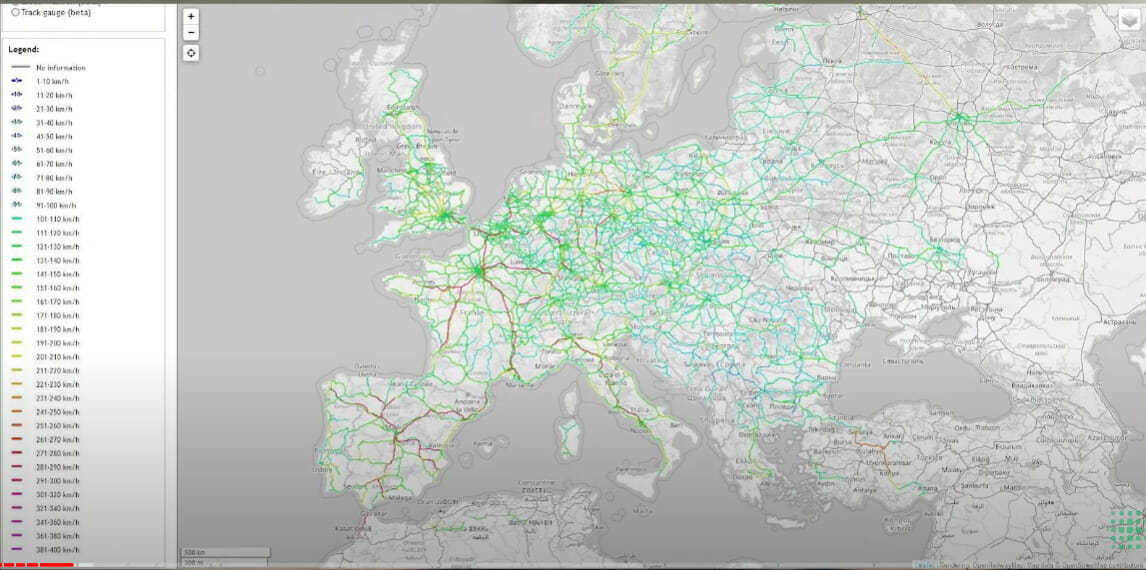
Tilman Versch [00:04:25] So compared to the US, in the European system there’s a lot more passenger transport and people are riding at high speeds like 200 kilometres or something like this. So what’s this mean for the railway tracks and the systems, especially with your strength and tension clamps and the sleepers? What does this mean by the higher speeds and the higher share of passenger traffic?
You asked for the differences in the systems, just to give you some indication here. In the fastening systems area, in the past, we had more than 60 different systems for each and every application, and of course, it just depends on the specifications of the specific country. But of course, the temperature is an issue as well, and the usage of the lines has a huge importance on the detailed specifications of the track. For turnouts, for example, we use, it depends, or the crossings are different. If you have a conventional line or if you have a high-speed line and there are even differences in the technology in Europe. So in principle, you have German and French technology and both are slightly different, but of course, serve the needs of the customer.
And I would say, in the US, we have the array mashed on that and all in all, I think it’s fair to state the quality of the infrastructure in Europe is at a higher level at the moment than in the US, so I would say in Europe the catch up already started, but this will definitely continue with all the discussions on CO2 reduction goals going forward. And we, in the US, I would say we are just at the beginning, but nevertheless, they are huge, huge programmes like the Biden infrastructure which will support our business in the future, especially when it comes to passenger transportation with our customer, Amtrak, which runs the Northeast Corridor in the US.
A tension clamp fixes the rail to the sleeper
Tilman Versch [00:07:53] Maybe a quick follow-up on your products. I think many people can understand what a sleeper is or a turnout. What is a tension clamp and why is a tension clamp important for the railway system? Yeah. So I think you also have the tension clamps in the back somewhere, so people can better imagine them.
A 40 million factory and a new generation of clamps
Tilman Versch [00:09:34] Maybe let’s take the example of the tension clamp, how much R&D is in such a piece of steel?
So the product, which is in use at the moment and in many cases now, was patented back in 1967, and we ran out of the patent decade ago, so innovation was at a very low level. But when it comes to specific topics and specific details we are seen as the technology leader in this area for good reasons.
So there are some companies which copy our products, but if you have some and sometimes you have a breakage of a tension clamp then, of course, to understand the root cause and to make sure that this doesn’t happen again and to find solutions with the customer. I think we, here at Vossloh are leading and a very good example of our innovative strength is that we and we have presented this during the InnoTrans which took place last year in September, in Berlin and it’s a so-called new generation, an M generation tension clamp with outward, outwardly bent springs arms and this is completely new. It’s a new design. It strengthens the robustness of our products. It requires less material and it has a better CO2 footprint. And this all and all gives us some confidence that we will be successful to bring this to the market rather soon, and this clearly underlines that we are the technological leader in that area.
And if you and your colleague are invited to visit us here in Werdohl and do a plant tour together with me. And then if you see the production flow, how it is organised as of today and the machinery we use. First, do the bending of the material and the cutting and then the heat treatment. Afterwards, the coating is the final step. Yeah, it’s not so as easy as you would imagine when you just see the product in the field.
How is demand for rail maintenance and new lines changing?
TL;DR: Order intake reached roughly one billion after nine months of 2022, and about 85% of the business is replacement (2023).
Record order intake as Europe catches up on wear and tear
Tilman Versch [00:13:24] So this is a product you want to win market share with, but another topic that I find interesting is maintenance. Like, if we take the example of Werdohl where you’re located, there’s a train running every few minutes, but when you think about going climate neutral or getting more sustainable mobility you have to increase the speed and so also the maintenance needs to increase because the system is used more intense. Is this also something for Vossloh’s quick profit?
Good Investing Plus
Meet the experienced investors
Plus is our application-based community of 200+ investors. Around half run or support a fund, or allocate capital.
- Online: idea exchanges and events every two weeks
- In person: gatherings in the US and Europe
- Omaha: our 150+ member conference in AGM week
So and you are absolutely right. There are a lot of initiatives to bring more traffic on the rail. So what does this mean? In Germany, this is if you can’t build new lines in a short period of time. So this usually takes a lot of time and in some cases more than 10 years and the space is limited. So what needs to be done is first of all to upgrade and renew the existing lines. This is what has just been started and all our products have an on-average lifetime, I would say depending on the usage of the track between, yeah, let’s say, 25 years. So this means all our products are going to be replaced every 25 years. So 4% of the track is going to be renewed every year. And now with the higher utilisation of the track, the lead time of our products will slightly reduce going forward and just take into consideration that the average lead time would go down to 20 years only. Then 5% of the existing network needs to be replaced each and every year.
So currently we are in the phase of catching up. So spend what we should have spent it in the past. But going forward, we expect that the demand will stay at a higher level and as more the track is needed, the higher the replacement rate will be. And there is one important other important aspect and this will clearly change our way of doing business going forward. Because for the operators, the availability of the track will be key in the future, so they can’t afford a closure of a track because of the non-availability of some components because the track is urgently needed to transport goods and passengers. So here and this is new for us because the railway industry was seen as no, not really innovative in the past.
Now this is changing with the terms of digitization. New innovations are coming to the market and we are one of the leading companies in that area because the availability of the track is getting more and more important for the customer. And here, Vossloh, next to the component business, so we have all the relevant components for the rail track in our portfolio, which means fastening systems, concrete ties turnouts, tension clamps, fastening systems, turnouts and concrete ties. But we offer services for the rail track as such, so we have services in our portfolio to extend the lifetime of the rail and all of this we’ll gain some importance going forward.
So let’s take Deutsche Bahn as an example. They need to make sure that the rail in the field can be used longer than in the past, so typically what you do is that after a certain period of time, you exchange and replace the whole rail track. So the rail which is on the track after, let’s say, 25 years. So now what started a couple of years ago is that there are certain services available like milling to reduce the failures on the track by removing some millimetres of the surface of the rail, which extends the lifetime to a certain extent, but even more this is not really preventive. And therefore there are now some technologies in the market and here we have a USP in the field of high-speed grinding. So maybe I can give you some information about what high-speed grinding is all about and then we will see the importance that is especially has in Germany and will have in other European markets as well.
So for high-speed grinding, we offer services to grind the surface of a rail track with a speed of up to 80 kilometres per hour, and this is unique. No one else can do that. This service is already in China and now we had a breakthrough and did a press release last September to offer their services in Germany as well. So the big advantage for the customer Deutsche Bahn is that they don’t need to close down the track while they’re doing the maintenance, and this is new. So when it comes to conventional grinding or to milling, you have to stop the traffic on the line to do the maintenance and we have some services in our portfolio that clearly have some benefits for the customer because you can still run the line and in between was 80 kilometres per hour, we are able to do our services and here the speed of innovation is extremely high.
So one key aspect why we were successful to bring this to the market in Germany was that we recently have equipped our yellow machines, our high-speed grinding trains not only the big one, the high-speed running, but we have small applications for urban transport as well as the high-speed running city. The sensors and now we can first show the customer the result of our grinding measures and secondly, we collect additional information to give the customer information, additional information, about the condition of the track and maybe to give them some advice on which services should be done on top of that to make sure that the availability of the track increases going forward. And here we are, one of the leading companies we have shown the scene some good examples and nice projects in the past and this is certainly something where we see high growth potential in the future.
Chinese maintenance will come later, from a 20% share
Tilman Versch [00:22:08] If we talk about maintenance. I also have to think about the Chinese network where you’re already doing business and you told me that you’re already growing by the growth of the Chinese network which expanding a lot, but also if you think about the network, this was built 20 or 30 years ago. Is this also a chance to win there in maintenance and renewal contracts with the Chinese network?
So far, no maintenance is needed because the average lifetime is around 20 years for these components or might maybe even be slightly longer. The maintenance business is something that will develop going forward. It started at a very low level, but in a couple of years or a decade, the Chinese will reduce or stopped to build new lines once they have achieved this 70,000 kilometres network and then the situation will be similar to Germany where the replacement business will kick in. And here it’s worth mentioning that we currently have had a market share of around 20% for many years right now in the high-speed area and our system is slightly different from the system that the Chinese competitors have in their portfolio. So there is a certain likelihood that when it comes to replacement, our products will be in the field as well. So sooner or later the Chinese market will move more in the direction we have in Europe.
But in Europe, of course, many lines have been built hundred years ago or even longer, so the market here is very mature and in China, we are right at the beginning. But China will nevertheless be a growth market for us, maybe not in the high-speed segment when it comes to the building of new lines. But there are other areas, and the Chinese, they now start to build new lines between cities, which are at the moment, high-speed lines where the trains are running 350 kilometres per hour, there will be some connexions between the cities at the line. Some cross connexions where the speed is up to 250 kilometres per hour. We expect the first tenders in the market soon and then in the next quarters and we think that we have quite a good product here to gain a certain market share in that area as well. Like we did some steps over the last three years with the newly formed joint venture three years back named Anyang in the area of conventional lines and in the UTS business.
So China is an important market for us. It will stay an important market for us and yeah, but the mechanism of the market is at the moment still completely different from what we see in Europe. Here, the market is mainly dedicated to existing lines but due to all the political discussions and the high political will that we see when it comes to CO2 reduction targets, not only upgrading existing lines but building new lines will play a certain role going forward. Just worth mentioning one or two projects, let’s take the Rail Baltica project as an example. So Rail Baltica is the new line which is under discussion for roughly 30 years right now. So it’s a line from Warsaw to Tallinn through Lithuania and Latvia with a length of up to close to 1000 kilometres, and there will be a tunnel between Tallinn and Helsinki, slightly more than 100 kilometres, so all in all, the line has a length of roughly 1000 kilometres, slightly more from Helsinki to Warsaw, and this is a new line and this has been discussed for many years.
But each and every time funding was an issue, especially after the financial crisis in 2008, 2009, and 2010. Funding was not available and a strong political will to bring to have higher usage of rail as the by far greenest mode of transportation going forward. Now funds are available and this line will be built. Current plans are until 2026, so we should see some tenders in the market for all products over the next quarters. And this is just one indication of what is happening in Europe right now. There are plans in many countries. For example, in France, they are planning to build new high-speed lines as well to make sure that in the future domestic flights are no longer needed.
So the French market at moment is at a rather low level due to the high losses SNCF have suffered over the last couple of years during the pandemic, but recently they announced that they made some positive earnings in the last year and that they now want to invest more in the infrastructure as well. There are plans, a programme called X2 with a clear target to double passenger and freight transportation over the next years in France as well. So sooner or later we expect the market to recover and that some funds will be available to modernise and even upgrade the infrastructure and even build some new lines.
Retirements at rail operators open up service work
Tilman Versch [00:29:33] all this investment we are talking about happens behind the background or in the framework of demographic change also a lot of the state agencies will lose a lot of their skilled workers because they retire. And what chance or hurdle is a demographic change for Vossloh?
So DB is a very, very important customer for us. They have a lot of experts technology level at DB is high, but you’re right, retirement in the future will not be only a problem for Deutsche Bahn, but for many other state national railways as well. And there will be a lack maybe of competency or at least it must make sure that the knowledge stays within the state National Rail operators, but in some cases it might make sense to outsource some activities to suppliers like Vossloh. So we are seen, on the DB side, not only as a supplier but as a partner. So we developed together with DB for example the business of high-speed grinding and we are looking at other options as well. And we have a lot of services in our portfolio that Deutsche Bahn could make use of and of course, it’s up to us to demonstrate to them going forward that we are the right partner and we are able to solve their problems and maybe then we can increase our services business for Deutsche Bahn as well going forward at least is a clear target for us.
How has Vossloh changed since 2014?
TL;DR: The rolling stock exit cut sales from 1.3 billion to around 850 million, and growth was around 8% over the last two years (2023).
From rolling stock to a pure rail infrastructure focus
Tilman Versch [00:33:00] So we’ve been a bit on a higher or meta-level, with our discussion till now but let’s jump on the concrete like the more focused Vossloh level. So how has the company changed over the last five years, if you will compare Vossloh today to Vossloh five years ago? What is different with Vossloh?
Secondly, we want to be among the top market leaders in this market we are in and if possible on a global scale. We are number one in fastening systems worldwide and we are number two globally in the turnout business and in the rolling stock business, this was not possible at all. So if you compete with Siemens, Alstom, Bombardier or CRRC, it doesn’t make sense to compete with them. And a third reason was the risk profile of the huge contracts you have in the rolling stock area, this is something we didn’t feel comfortable with any longer.
And now in the rail infrastructure, the risk profile is much lower than in the rolling stock area. So we sold this off. And then a couple of years later or in parallel, we did a performance programme in 2019. And this was a huge change for Vossloh as an organisation. So we sold loss-making entities because we found out that we were not fit for the future. So our cost position was not the best in class, so there was hardly any growth in the company. Margins were stable or even slightly decreasing. So what we did is that we did an analysis of all loss-making activities, sort them off or restructured them or in some cases close them down and on top of that, we reduce the workforce by roughly 7% all over the world, so this was a huge step, but this was urgently needed to make sure that we are able to reach our ambitions going forward.
This took quite a while, I would say now the process is more or less finished. Still, we have some activities in France where we need to improve, but all in all, I would say the performance programme is done. But it was a critical situation for our employees coming from a company with sales of 1.3 billion, now shrinking down to around 850 and doing a performance programme, and they offer a lot of people. People ask us, our employees, and it was a fair question. What does the Vossloh stand for? What is the North Star? So we decided in 2020 to run a broad strategy project, we invited more than 100 employees and discussed with them back and forth what is key for our business in the future. Finally, we aligned on 30, roughly, slightly more than 30 strategic actions which we presented to the capital markets in December 2022.
And since then we are clearly following that path and this gives us purpose and orientation, this is one of the, I would say, success factors while Vossloh was able to grow much faster than the market over the last two years, and while we expect that going forward our ambition is to grow faster than the market and recently the unique they gave an update about the expectations of the market going forwards. They expect an average growth rate of 3.8% and we have clearly underlined over the last two years at least if you take the middle of our guidance for the fiscal year 2022 where we have seen growth in the ballpark of around 8% over the last two years.
And this gives us some confidence that we are on the right for two reasons. First of all, we did our homework and now secondly and this will be a key driver going forward. We see that the first tenders, which have been discussed for many years now, now come to the market. The railway industry and especially our industry, so they have long lead times. So we recognised and this started, I would say three or four years back. That many projects were discussed in detail which have been more or less dormant for quite a while because of funding issues. Now the customers came back and discussed with us all the specifications, normally it takes, let’s say two to three years until the tenders come to the market. Then the tender award might take additional 12 months and then if we start to deliver our products, it might take two or three years or even more.
So from the pre-tendering phase to the final delivery of our products sometimes it’s more than five years and what we saw or currently observed is that this has started for several reasons. So there are huge infrastructure programmes all over the world announced, have been announced a couple of years ago. And now, yeah, to a certain extent, we see some growth, but even more in our P&L on the top line in the sales, but even more we see a record order intake and the record order backlog. So we are quite confident that we can continue this trend. And that we will see some additional growth in 2023 both on the sales side and on the EBIT side and in the current global environment where polycrisis is one of the major buzzwords. I think this is a very good development that we are really confident that we will continue the way that we started two or three years back.
To sum it up, there was a huge change. We clearly transformed our company. This is not finalised for sure, so you can’t implement a strategy completely in two years, but I think we are addressing the right topics, market topics, and product development topics, improving on the services side and improving our organisation with several measures that we are fit for future are more competitive and can increase our market share and show some profitable growth in the future.
More funding, but planning a new line takes as long as ever
Tilman Versch [00:41:26] As societies, we are also working towards the climate target. In 2015, many societies want to become climate neutral and invest in this way. And I think the railway has a crucial part to play here, so does this have an impact on the clock speed in which your industry is operating? So have things sped up over the last years?
And in Australia, for example, where the Inland Rail Project where we are in a very good position. So all in all, funds are there, but does this mean that the speed to build the new lines increases? I would say, only to a minor extent because the planning which is needed to build a new line has not changed, so there are a lot of requirements to be done to make. And very often, especially in Europe, 10 years is nothing from the first plans to finally build some lines. And we have seen that in many countries that even if funds are available so planning capacities are limited. So in this regard, I will say, okay, we know that more projects will come, but the speed of one single project I think there is no speed up, but all in all due to the high number of projects in the market, hence the changed requirements of our customer that they are now more and more focusing on the availability of the existing network. This clearly changes our industry and gives innovation much higher relevance than this was done in the past. And here, companies and the railway infrastructure like Vossloh clearly need to adjust and therefore it was quite good that we already incorporated this in our strategy that we are agile when it comes to finding new solutions for our customers.
Political will keeps the funds available
Tilman Versch [00:44:39] As the quality of your demand and then also the quality of your revenues improved over the last year. So if you go back 10,20 years investments in infrastructure, especially railways were always a topic when it comes to downturns of the economy that they were cut and they weren’t seen as needed. But now, with the focus on climate neutrality and climate change. I think this could have an impact on the quality of your revenues and the quality of your demand because people really wanted this and need to do this instead of just seeing it as a can-be investment.
This does not mean that maybe one or the other project will be delayed going forward because we were affected hardly as well by the rising of raw material prices, not Vossloh only but the whole infrastructure business and therefore some projects might be put on hold, which is not the case at the moment, but we cannot exclude since this might happen in some areas, but all in all, we don’t see that this trend will end, it’s more the other way around. Funds seem to be available and new projects are going to be planned. And our good indicator is our order intake and our order backlog. So for order intake and order backlog after nine months last year, we have shown record numbers and we most likely will never start into a new year with such a high level of order backlog.
I think here it’s worth mentioning that at Vossloh if you look at our order backlog, these are only firm orders. So on top of that, we have roughly between 300 and €350 million in sales which come out of frame contracts which are not part of the order backlog at the beginning of the year because we only put them into our order intake and order backlog once we have received the call-off from the customer. So this. This is a very good indicator and if you look at the sales level we have in our books when we look into 2023, this has increased compared to prior years and therefore we think we will grow the company once again in 2023.
How does Vossloh handle inflation and investment?
TL;DR: Wire prices rose more than 100%, the 2022 EBIT margin guidance was 7 to 7.5% and capex should rise to 60 to 70 million (2023).
Higher prices, down payments and price escalation formulas
Tilman Versch [00:48:32] If we talk about inflation, it also can be an interesting topic to better understand your negotiation power like inflation is still high, but we might be coming down a bit and you’re mainly impacted by steel price inflation because energy is not a super huge thing for you in the cost basis of your products. How has this been on the negotiation side where your partner’s willing to renegotiate or have they tried to put you down and put pressure on your profitability or do they see you as a partner? Do they also want to be happy?

There was a period especially after the Russian invasion started where it was very hard for us to finally judge the potential impact on our P&L going forward, but we did a quite good job. So all in all, and I think this was to mention the absolute EBIT we are, if you take the middle of our guidance, we are even slightly higher than the 2021 numbers. And 2021 we have an EBIT of €72 million despite the fact that we had a huge additional burden from the material side. Of course, we cannot neglect that it had a certain impact on our margin because even if you are able to pass everything through, you have a deterioration on the margin side.
Let’s take an example, you have 1 billion of sales with 80% EBIT and the margin is 8%. And if you now have 50 million additional costs, which you can pass on by 100% then you have 1.05 billion of sales, but still 80% EBIT. And your EBIT margin goes down to 7.6%, although you have done a quite good job. So there was a certain impact on our profitability in 2022. So our latest guidance is 7 to 7.5% which compares to 7.7 the year before. But yeah, nevertheless, if you take the middle of our guidance and let the EBIT, it will be the highest EBIT in the Vossloh group since 2012. So there are a lot of challenges we found a way in 2022 to handle this.
Looking forward, you mentioned the energy costs. At the moment, energy costs are at a rather low level, but of course, we needed to secure some prices in October and November of 2022 to make sure that energy is available in 2023. So from today’s view, our challenges will not stop even for the material. For some components like wire, we see prices are going down. For some other components, there is a certain delay in the prices for our products. So and for many components, not only plastic components but for some steel components as well, we expect a further price increase in 2023. So we have to handle but all in all, the magnitude should be should lower than in 2023. And total offset of course due to the high inflation you mentioned, there will be an increase in global salaries. That’s for sure. So this will be higher than the average numbers in the past, so it will be an additional burden on our P&L as well. But we are quite confident that we can handle that once again,
From the inflation top line, I think the impact will be a little bit lower than in 2022 because we were faced with high increases in material prices already in 2022 and were able to pass on the majority of it to our customers. So one portion of the growth that we will have realised in 2022 and by the way, the first time in the infrastructure, we will exceed the 1 billion in sales was driven by the pass-on. But the other portion is still coming from the, not still, is coming from the operations and the very strong demand in many countries that we see currently.
Capex of 60 to 70 million, above depreciation of about 55
Tilman Versch [00:54:36] You already mentioned this huge order backlog Vossloh has. What impact does this order backlog have on investments because you’re delivering your physical product and that’s easily scalable, so you have to do investments to fulfil the demand?
In our turnout business, we have several production sites all over the world, mainly in France, but as well in Scandinavia and Sweden, and Australia. In some areas, we are already running at a high capacity utilisation, so we slightly changed the organisation in this regard. Now we have a functional organisation, we have one CEO in place who clearly oversees the situation all over the world and try to be flexible that whenever necessary and possible that we shift some works to the next site, but nevertheless, we will take or we will need to do some further CapEx in the turnout business. And in Australia, we will invest after we have won the huge contract for inland Rail. So all in all, from a group perspective, over the last I think it’s worth saying that over the last two years, we invested slightly less than the depreciation rate and we expect this to change going forward. So the depreciation rate is at the moment around 55. So I would expect CapEx more between 60 and 70 going forward taking into consideration that in some areas and we need to increase. So there’s a capacity slightly and therefore needs some additional CapEx.
What are Vossloh’s margin goals and risks?
TL;DR: At least 10% EBIT margin in all three divisions, about 9% for the group, with holding costs of 16 to 17 million a year (2023).
Double-digit EBIT margins in all three divisions
Tilman Versch [00:57:28] I think over the last like five years or 10 years, you’ve put 150-year-old man Mr Vossloh in a boot camp to become more profitable and stronger as a company. So what is your goal in terms of profitability and profits you want to achieve with Vossloh?
Political will on CO2 reduction is the biggest risk
Tilman Versch [00:59:32] You have this margin goal at maybe let’s try to invert this a bit. What could happen or should happen that you fail with this margin go that you don’t get the margin you’re operating in? So it’s more like a thinking exercise, thinking about what risks are there and how they could happen or hit you.
On top of that, we have done the factory of the future here in Werdohl and we are now very cost competitive, so we have some benefits of around 5 million per year coming out of the new factory. But we suffered to a certain extent from the high gas prices here in Werdohl because the heat treatment is done with gas. So if the gas prices would explode once again and there were would be no additional measures from the government to reduce the impact, this would be a challenge for the fastening systems business. For Tie technologies, Australia is a very good and solid market, so I don’t see any risk on that side. In the US, I mentioned at the beginning that the demand for our products was very low. So if it would stay at these levels, then there might be a risk that we don’t end up with a 10% margin then overall in the core components division.
But sooner or later there must be a pickup in the market. So this is what we have seen in the past as well, that the market is quite volatile. But this will be a requirement to clearly surpass the 10% in the core components division. For customised modules, as well France, which is our home turf and our biggest production sites are in France and we acquired a French company 21 years back. Yeah, if the French Government would stop to support spending on the rail infrastructure, I think, but this is not only true for France, but Europe in total, this might put our target in danger to be double-digit in that area and many other areas. We already see that the demand is quite high. So in life cycle solutions, a major driver in 2023 will be high-speed grinding, so this will all in all and the strong demand not only in Germany but in other countries as well.
This will bring us much closer to the 10%. The biggest risk, of course, is the overall trend to CO2 reductions and the political will to bring more traffic on the rail. If this would change, then this would certainly have an impact on our business and we would need to take some additional steps to nevertheless at 10% target when it comes to EBIT margin. But it’s up to you to decide how likely this is if the sustainability efforts of all the governments worldwide will change or not.
Number one in fastening systems, with high entry barriers
Tilman Versch [01:03:56] Your margin is my opportunity. And it’s a well-known Bezos quote and with a high margin of 10%, you also run into the risk that more competition comes into this space and tries to outcompete you. Where do you, especially see such competition risks and where do you see certain risks coming from competitors on your margins?
In the turnout business, we are clear number one on a global scale, there is one company, and it’s a subsidiary of the Austrian steelmaker, Voestalpine. They are number one in that market. Because they really have a strong footprint in China and the US and we are not present. For example, in the US and in China, we only have equity consolidated companies. In lifecycle solutions, it’s twofold. So we are number one when it comes to milling, which is one measure to increase. The lifetime of rail and when it comes to tracking supply, which means welding, stationary welding and logistics of welded rail. All in all, the market entry barriers in our industry are quite high because typically all our products are safety-relevant.
Good Investing Plus
Meet the experienced investors
Plus is our application-based community of 200+ investors. Around half run or support a fund, or allocate capital.
- Online: idea exchanges and events every two weeks
- In person: gatherings in the US and Europe
- Omaha: our 150+ member conference in AGM week
And if you want to equip or deliver to a country, you first have to prove that your products are fit for use. So you need a test track and after a couple of years, you maybe get a homologation and then in many cases and this is especially for turnouts and for sleepers, you have to take the decision if you want to invest in a country because in many, many areas local production is needed. It doesn’t make sense to ship, for example, concrete ties from Australia to Europe, so you need to invest. And then once you took the decision, you can participate in tenders and you then you meet Vossloh, which has a really good market position in the field and a very good, I would say cost position as well. So there are some hurdles for new participants to enter, but nevertheless, of course, if the market is attractive and if we are really able to achieve double-digit margins, some other companies, maybe even from other rail industries will certainly look. It’s a business but I would say we are. We are prepared to manage this situation as well.
Who owns Vossloh and does management hold shares?
TL;DR: No sign of change from the Thiele heirs, and no board member bought shares for more than a decade (2023).
Tilman Versch [01:07:50] Sadly, we’re running a bit out of time, so I want to end this interview with three short questions and you can answer them quickly.
No sign that the long-term shareholding will change
Tilman Versch [01:08:03] The first question is about the shareholder structure, certainly the largest shareholder, Mr Thiele died I think two years ago and there’s a bit of a struggle in the family about their wealth. And do you see a certain [01:08:18 inaudible] with the family sitting at a certain time and this could put pressure on the other shareholders because they sell or are they more long-term oriented?
About 50 shares, plus share-based long-term incentives
Tilman Versch [01:09:40] Do you or other parts of the management own shares?
No board member bought shares in more than a decade
Tilman Versch [01:10:29] When has management last bought shares and why?
Tilman Versch [01:11:20] Yeah. Thank you very much for coming on the podcast and thank you very much for answering my questions. And also to the audience, I want to thank say thank you that you stayed still here. I wish you a great day and bye-bye.
