
Are you Italy’s best capital allocator? – Marco Pescarmona (Moltiply Group)
- Marco Pescarmona and his team bought Trebi, the leading software provider for the leasing industry in Italy, for around €80 million in the two years after 2021.
- About 8% of Moneysupermarket was bought with net cash, a stake worth more than one time EBITDA (2023).
- Price comparison handles about 10% of insurance or mortgages in Italy, 5% to 6% in Spain and under 3% in France (2023).
- The Italian mortgage market fell 70% from 2011 to 2012, Marco recalls.
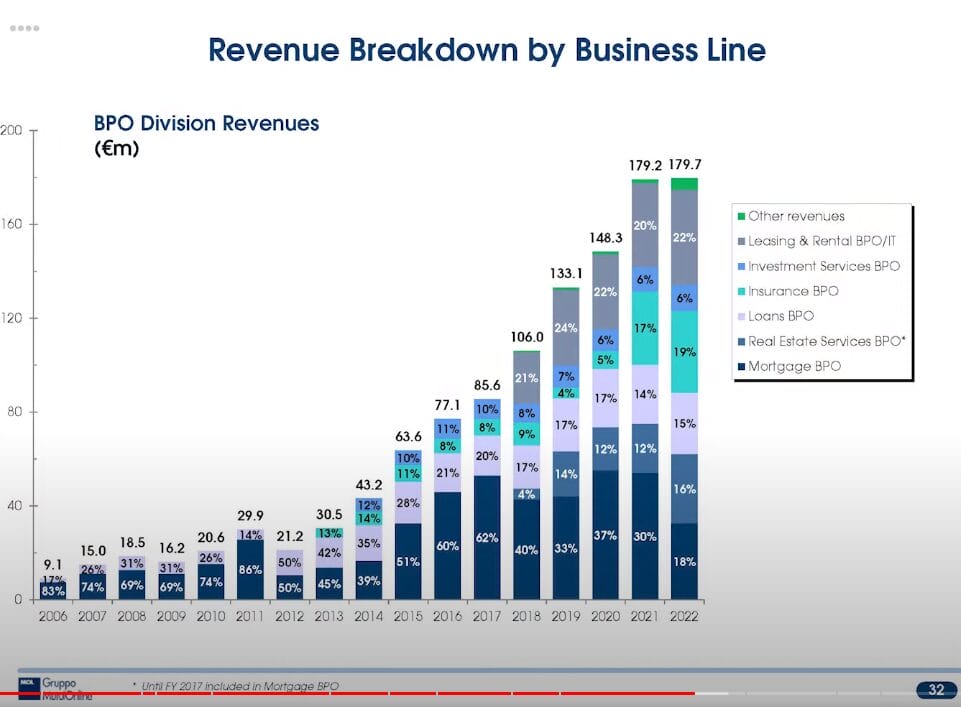
- Mortgages are less than a quarter of the business, despite the name Gruppo MutuiOnline (2023).
You are currently viewing a placeholder content from YouTube. To access the actual content, click the button below. Please note that doing so will share data with third-party providers.
More InformationGruppo MutuiOnline (now Moltiply Group, MOL)
Moneysupermarket (now MONY Group, MONY)
Admiral Group (ADM) · Allianz (ALV)
What changed at Gruppo MutuiOnline since 2021?
TL;DR: The last two years after COVID were busy with acquisitions. The biggest challenge in 2023 is complexity, and organisational design matters more than finding talent.
How did the group change after COVID?
[00:00:45] 
[00:00:54] 
Why is a bigger group harder to run?
[00:01:27]
[00:01:36]
[00:01:57]
[00:02:01]
[00:02:38]
[00:02:49]
And complexity comes very easily where you need to intervene in situations that are not so easy, so it’s not a clear the thing, but things can be improved and the point is that the organisational design part I would say more than finding the right people.
Which businesses did Gruppo MutuiOnline acquire?
TL;DR: Europa for about €15 million, Trebi for around €80 million and the former Admiral comparison sites Rastreator and LeLynx, roughly 250 million in total since 2021.
Which three businesses did it buy?
[00:04:03]
[00:04:22]
It was not big because it was about €15 million in enterprise value, but it was a leader in the field with a lot of potential and also we acquired all the technology behind it. And that’s something which we are building. And it’s an acquisition similar to the ones that we did in the past. So very, very good valuation, I would say, for a business that requires some work. And so there’s an interesting story. But I would say it’s a bolt-on where we found an opportunity and we like the entrepreneur and we thought let’s do it.
So there’s one, but the more important one is a company called Trebi that we acquired for around €80 million. Because in a bit more than that, I think. That’s a company that is the leading provider of software solutions for the leasing industry in Italy. Leasing is a regulated business and requires very specific systems to operate. So the idea was that we had Agency Italia, which was the leading BPO provider to the leasing as well as the long-term rental industry and we also typically the main supplier to many of the players in that industry and we could combine it with basically our clients were using the Trebi systems as the leasing clients.
And so we could generate efficiencies for ourselves and for our clients, by having control over like the software, the operating system, I would say of these businesses and the operational path. And also the idea was that we could leverage our knowledge of the rental industry, long-term rental industry, which is like a sister of the leasing industry, but not exactly the same and also develop a software solution for that sector.
So it’s the first time we really tried to combine BPO technology and operations and see if we can create value out of that. And we’re still at the beginning, but I think we are happy that we, took that route and we’ll see how it goes, but we are optimistic in the end. And that’s the second acquisition.
And then the third and the biggest and really the boldest move I would say is the acquisition of a number of international assets that have originally belonged to Admiral Group. This is within the brokering division. And these are some comparison businesses. It’s Rastreator in Spain. Rastreator is the leading price comparison website in Spain. Then there is the LeLynx which is a co-leader in France, it’s mostly focused on insurance. And so I’m talking about insurance here.
And then we also acquired as part of the package, one of the co-leaders in Mexico, it’s called Rastreator Mexico. These are three companies that were profitable when we acquired them. And we think have a lot of potential for two reasons. One, we think this is also what we are seeing, we are able to apply our best practices to these companies and the results are already improving in a substantial way, and this means higher profitability without killing growth. So with some revenue growth, significant EBITDA growth and this is the first reason why we like these companies.
Second these companies are in markets that are even less developed than Italy for comparison and intermediation. And so there is also optionality, meaning that this is outside of our control or only we can influence this only to a limited extent, but these markets, could maybe in 10 years, 15 years, 30 years really unlock they could become multiple of what they are in terms of market size. So we have this option on the unlocking of the markets that we also got with the acquisitions and which we consider very valuable.
How does Trebi deepen the moat?
[00:10:03]
[00:10:38]
So this ability to offer integrated solutions or come up with creative things is helping us more. But again this is a relatively small acquisition. So maybe it makes a difference but not so big in terms of barriers to entry and so on. But when we look at, for instance, Trebi is clearly designed also to increase our moat, because we now are the, basically, we were already with Agency Italia, the leading supplier to our clients in terms of size and relevance for their business and with this acquisition was typically the second more most important supplier.
For the same businesses, so here we have an even deeper relationship with our clients and we can have a stronger partnership with them. And there is no one in the market that we think can offer anything comparable and the synergies in terms of know-how, in terms of ability to come up with commercial propositions that are really compelling and so on are potentially very high. So I think within the leasing and rental industry, this clearly reinforces our position and again a position as a partner to our clients but clearly there is a moat there and it’s now deeper.
What made the deals possible and why buy 8% of Moneysupermarket?
TL;DR: War, inflation and higher rates brought more sellers than buyers. Spare net cash went into about 8% of Moneysupermarket, with an energy recovery expected in 2024.
Why were sellers easier to find?
[00:12:51]
[00:12:55]
[00:12:57]
[00:13:02]
That could be one or it could be in other cases, I would say, well, not only had COVID, but we actually had a lot of stresses. Like we had the war in Ukraine and energy crisis and so on so, interest rates jumping up because of inflation and I think all these things increase the tensions in different places of the system and these tensions were sometimes just psychological in many cases, maybe they could have been also financial. In times of instability, there are more assets available for sale, I would say. And better opportunities for people who have the strength and the long-sightedness to look at opportunities in those moments.
So I think it’s a mixture and we don’t really know the exact reasons, but I think it’s a combination. Again, it’s because I would say there are times when there are more sellers than buyers and times when there are more buyers than sellers. I think the last two years, especially after the beginning of the war and then the inflation and the high interest rates they became more as sellers. More sellers than buyers,
I would say. I’m actually surprised because for us it’s more natural to buy companies. For me, it’s difficult to understand normally why one would want to sell something, especially a good asset. But clearly, it’s not the way most of the people see things.
Good Investing Plus
Meet the experienced investors
Plus is our application-based community of 200+ investors. Around half run or support a fund, or allocate capital.
- Online: idea exchanges and events every two weeks
- In person: gatherings in the US and Europe
- Omaha: our 150+ member conference in AGM week
[00:15:42]
[00:15:45]
Does the group always buy 100%?
[00:15:48]
[00:16:05]
And the way that was the only option available. But our preference in general or we are quite used to doing transactions where we work with entrepreneurs, where we acquire a majority, but then we run the businesses together with the founder or whoever was managing the company and they retain a stake and then we have typically put and call a few years down the road that could be extended in case we get along well.
But that’s our preference because it creates an alignment of interest and so on. But it’s not always possible to do it, and also sometimes we see it wouldn’t work with one person or another or a situation or another. And sometimes people just want to receive cash. But for us, we think that’s the best because it removes some potential pension overvaluation and also it allows the entrepreneur to reap the benefits of additional value creation which we could also help with synergies or knowledge transfer and so on.
Why buy a stake in Moneysupermarket?
[00:18:09]
[00:18:23]
And so we had a financial position of net cash which was sitting on the bank doing nothing, basically. So we thought with more flexibility and I had always been following money supermarkets and the stock all of a sudden crashed in a very significant way. That was explained by a contingent situation in particular. The energy crisis meant that all the energy supply disappeared from the UK market and so money supermarkets, which were making pretty good money from the energy vertical. It was one of its biggest verticals and a big drop in income.
At the same time, there was a change of regulation in the UK regarding motor insurance. And so there was a lot of concern about the company in the short term, and financial performance deteriorated. We’re still making very, very good money, but significantly less than before. We thought the stock price didn’t reflect the value of the company.
And not even at the level of profitability of the time, so even at the level of profitability with energy not functioning, insurance only suffers. The stock price was still too low compared to what the company was able to generate. So we started looking at it in more detail, building models and so on like an investor would do and being from the same sector means it’s easier maybe to understand exactly how things work or read through the words of the annual report and so on and come up with good expectations and the good model. So we really think about the model, look at the model, double-check it, try to speak with people and so on.
And then we said this is a good investment because the energy will come back and the company by the way, just changed its management. So we also thought that the new management was a positive. So we started buying shares and we bought 1% and then 2% and then 3% and so on. And in the UK, you have to disclose it every time you pass a 1% ratio.
So we kept buying until we had enough, which was around 8% and its financial investment in a company that is exactly in our sector, even if in another country. So we are not competitors in any possible way. They are clearly domestic. So they’re not an issue even for our now international footprint.
And we like it a lot and I think so far it’s been a good investment. The company has kept improving. The management has done a good job. And also with inflation, insurance has picked up a lot. The reforms have not been negative actually and now we are starting to see the beginning of the recovery of energy.
We are at the very beginning so it will happen most likely in 2024 and hopefully, that will bring the company back to a more reasonable valuation given its strong brand, strong position in the market and so on. So it’s been a financial investment with which we are very happy and we will see what to do with it in the future. But for now, we are very happy.
How does Gruppo MutuiOnline run acquisitions and add value as an owner?
TL;DR: Two or three people form the deal team, the synergies are soft, and 20 years in the sector make the group a focused, permanent owner (2023).
Who runs the deals?
[00:23:01]
[00:23:17]
Sometimes it’s demanding like when we did the international acquisition of Rastreator, LeLynx et cetera. That was a very complex setup because there were entities in four or five jurisdictions. The contracts that will be done under UK law and so on. So there was a lot of complexity, and of course, we had to hire lawyers to help us with that. But like, for instance, for the business part like this due diligence. We normally do it ourselves and we do a lot of stuff ourselves and very, very much and so on and quite involved in that part.
I would say now that we like, I used to run, as the first time the brokering division, then we hired the person who’s basically a general manager or more, even the CEO of the brokering division and it’s full to the responsibility. So I have more time and this more time has been dedicated more to transactions. But you’d be surprised. It’s super simple. We are not many people. We are very few and sometimes it’s very intense.
Where do the synergies come from?
[00:25:17]
[00:25:38]
Where it’s a lot about tuning small details, small secret recipes that make you better than others. And so we think we have a little bit of those ingredients and so far we’ve tried to apply them to international businesses with good results. We still don’t know if we have any particular advantage, but certainly, the synergies are not hard synergies.
They are much more difficult to find, let’s say, and also knowing that the business you acquire could be improved or not is not so obvious because again it’s not costs that you eliminate or bargaining power that you acquire or anything. It’s more like maybe you can do a better advert because it works and that advert sells more.
But it’s very hard to say the recipe that was working in the country will work in another one. This way we are happy with what we did. We are seeing the results but saying that we have a recipe, still a soft recipe. It’s working, but it’s a soft recipe.
What does a permanent owner offer sellers?
[00:28:14]
[00:28:21]
So they were enablers and not their core business. Still, they were you know operated by good people and with good principles, et cetera, but they were not the core. And then the businesses that have been acquired by a UK company that had acquired a bunch of assets altogether. Including a large UK aggregator, they were interested really in the UK assets. Because they were a UK company, the international part was not their core business again. And it was small for the complexity that it entailed.
So I think the key difference so far, the easy one to say is that we like these businesses, they are really our focus. We put all our attention into them, and we try to have a simple strategy with strong execution. And I think this focus, and this being a specialist with 20 years of experience in the sector, I think is what makes a difference as a better owner.
And by the way, we are a permanent owner of these businesses. So these are businesses it’s not like private equity where they buy the company try to pump it up, and make it flow. But also maybe go plate it and so on to sell it later and create or accept fragilities. We don’t accept fragilities. We try to build, invest in, or shape the businesses for long-term growth and profitability and that also makes us a better owner.
How do the markets in Italy, Spain and France differ?
TL;DR: About 10% of insurance or mortgages go through price comparison in Italy, under 3% in France. International peers run at 25% to 30% EBITDA margins (2023).
How far has online comparison spread in each country?
[00:30:48]
[00:31:01]
What is it in Spain it’s probably between 5% and 6%. These are like very ballpark figures. And in France, it’s maybe less than 3% for insurance. And why is it different? I think consumers are very similar. Consumers have the same, more or less level of education, the same level of access to technology and so on but for, like insurance and financial products in general, the difference is normally more on the supply side. So like in Italy, we have a highly competitive supply with a good number of direct insurers and that allows the market to keep growing.
Still, we don’t have the traditional insurers on board, and it will take many years before the penetration becomes comparable to the one-off, say, not even the UK, but say of Germany. But if you go to Spain, still you have some large direct insurers that don’t really work with the channel to its full potential, and by the way, in this way, they’re probably losing the big opportunity and the risk remains behind.
So in Spain, even the direct insurers there are a number of them and most of them work with aggregators, but not all of them and there is clearly an issue both for the aggregator and for the growth of the channel. But also for these players, I would say. And in France, it’s a similar situation, but worse I would say because there are very few direct insurers in France, there are like two or three pure direct insurers and then there are many traditional insurance companies and being conservative, I would say. So the direct insurance themselves are not enough to have a good development of the market.
There are also modern brokers that are helping, but they’re not the same as a fully-fledged direct insurer. So there is a big supply too, and I think also the aggregator maybe in France has not done such a great job in speaking with insurers because the insurers should benefit from aggregators and even traditional insurers, they could learn and benefit from working with aggregators. And it’s something that is happening anyway.
But being these companies like the one that we acquired, but not only ours like Anglo-Saxon origin, they were possibly run in a way that was too linked to an idea of the mark that was the UK model that was too advanced for Europe, so possibly we were not speaking the right language also with insurers.
So I think we would need to have a dialogue with existing insurers. We will need to see new players coming into the market, which is a very nice market. But again, I would say it has more to do with the supply side than with consumers.
And finally, it also has to do with your ability to execute. Ao within the market, the development of the market depends very much in this case where there are supply constraints on the supply side. But it also depends on how good you are at serving the consumers. So providing a good service, an easy service, making it well-known and so and so. Probably also the operators are to some extent responsible for a lesser degree of development of the markets.
What was harder than expected abroad?
[00:35:55]
[00:36:26]
And nothing that we were not expecting. But let’s say also coming from an Italian background, I’m not saying you have a credibility problem in other places but a little bit you have to prove yourself, and that’s maybe less needed in a country like Spain, which has more similarities. In France, maybe it’s a bit more difficult and again we are doing pretty well in France.
So it’s not a big issue and possibly also France is a more complicated labour market but that’s where we are. Sometimes it takes us longer than we expected to recruit people, even if it’s a very, very good opportunity. But it’s very minor things really.
With these acquisitions, we were actually surprised that we didn’t have so many surprises. So by the way, this is like a random thing. Sometimes you have surprises with acquisitions. But sometimes you even have surprises with your own businesses. There’s a point of surprises because they could come from regulations or like new entrants, irrational things. So they could be anywhere. So far, especially with the international acquisitions, I would say very, very few surprises on the negative side.
What is the plan for the acquired businesses?
[00:38:54]
[00:39:07]
I think we can help to develop the market and retain or develop a very strong position in each of our reference markets. In a company, the market in its development and potentially see it unlock at a certain point. The idea is that this will be domestic markets for us, just as Italy is and it’s fun for us to look at Spain and France, Mexico and understand the markets and so on and help that the companies develop.
And we are really trying to become on the brokering side of international players. We are at the beginning; we really have to be successful here. We have a lot of work to do but it’s something that is it’s a challenge we really like. Part of it, we do it for like the financial performance, but part of it, we do it for the fun of it. The fact is that it’s a new challenge and we want to see if you’re good at it.
How does Marco Pescarmona think about amortisation, BPO abroad and debt?
TL;DR: Cash EBITDA is the cleanest view. Debt is about two times EBITDA net of the Moneysupermarket stake, with a long-term aim of 1.5 to 2 times (2023).
How should investors read the amortisation?
[00:41:02]
[00:41:11]
Typically, what you will see in companies like the ones that we have acquired is that you recognise there are software assets that are intangible and there are trademark assets like the brand name and so on. And so you make an acquisition and you like those are the numbers to 100. Net equity is 20, so there are 80 to be allocated and you end up maybe allocating, I don’t know, 40 or 30 to the software, another 30 to the trademark, and the remaining part, the 40 that remain are goodwill.
The software and the trademark under IFRS are then amortised. The software is typically in, say in our case, in five years the trademark may be in 10 years, but you create a lot of depreciation. In this example, you would have like 1/3 of 30. So that’s 1/5 of 30 is 6 every year, just for the software and another three for the trademark.
So just this acquisition of 100 million would generate 9 million per annum of depreciation of intangibles that you had bought together with the company and it’s just an allocation. So I would say the best way if you want to get a clean look at the profitability of these businesses, the best is to look at say EBITDA minus the investments or EBITDA minus CapEx. That’s one way to look at it. Or you look at the EBIT and you add back the PPA amortisation.
That’s why we disclosed that kind of information because that’s closer to the cash generation of the business and that’s the best indication I think of the actual performance and the best way to make a comparison and when we make acquisitions. Also, we try to look at things in that way.
Will the BPO division go abroad?
[00:44:33]
[00:45:02]
Then in general, I must say we have always kept, I mean, someone can then want to sell us a super interesting BPO business in Spain for almost free. We will consider it, but it has to be super compelling. So this our due now that BPO space is local and brokering internationally, but possibly considering other countries, if opportunities arise. But I would say, again, if there is a really compelling capital allocation opportunity that maybe means that we do something abroad for the BPO division, we’ll consider it again. But it’s not what we are looking for, so any gift, we take the gift.
How much debt does the group carry?
[00:46:47]
[00:47:15]
So in the covenants, the debt level is considered to be two times a bit down or a bit less at the end of the year. And of course, the investment in a money supermarket cannot be sold immediately. If we wanted to but it’s quite liquid and it’s something that if we wanted to do a really significant acquisition, we could dispose of. So I think it’s the right way to look at the situation.
So I would say from our point of view as well, from the point of view of the banks, the debt level is around two times EBITDA. And we have a business that continues to generate cash and we will continue to pay low dividends as soon as we are with a significant amount of debt. So there will be a natural deleverage.
I would say the most natural outlook is we sit on our money supermarket participation because we like supermarkets naturally the cash flows we generate from the business progressively the leverage and so it goes down. And then of course, if there are M&A opportunities that come up, we will instead spend the money to acquire the companies. And so maybe we will not leverage or we will go up a little bit, but I would say our comfort level is between where we are.
We are in a comfort zone. We could have a little bit more, I would say up to three times including the money supermarket stake, would be okay for a small period of time, but longer term we would aim to be, let’s say, again net of the money supermarket stake, aim more to be between 2 and 1.5 times EBITDA because that’s what gives you the flexibility to do things.
Otherwise, you are focused on managing the debt, which is not what we want to do. We want to have the possibility to catch opportunities when they arise. And to focus on growing our businesses. I think a certain amount of debt is actually helpful, it’s efficient. Exaggerating could be problematic, but we are not in the situation you asked about the interest rate risk. And of course, interest rates increased a lot and also our interest rate cost increased by, say, probably more than 10 million in a year, which is for us is still manageable.
But we wouldn’t want it to be more than that. And by the way, the other thing we’ve done so far is to stick to bank debt and bank debt is relatively inexpensive compared to other alternatives. But of course, it’s more conservative. So you could get, in Italy, very good terms for corporate debt. But they would lend you up to 3-3.5 times EBITDA or difficult to do more. And we think it’s a good equilibrium because it’s cheap and we don’t get too much of it.
And it’s consistent with the way we want to manage our leverage. Also, sorry, let me say one thing. In the past, but even recently we had situations in which very important pieces of our business suffered significantly. Like, I still remember 2012 when the Italian stock market, sorry, mortgage market almost disappeared overnight. So it was -70% from 2011 to 2012.
And those situations could happen. Now we are much more diversified, so it’s less likely, but you know if you had the time it would have been a very difficult moment. So you cannot have too much leverage also because if you have a serious problem then you could be in deep trouble. But again the level where we are is I think appropriate.
How does today’s mortgage slump compare with 2012?
TL;DR: Mortgage volumes were down about 40% year on year, against minus 70% from 2011 to 2012, and mortgages are now less than a quarter of the business (2023).
How much does diversification cushion the mortgage slump?
[00:53:09]
[00:53:30]
That means most recent figures were like -40% year on year. So not like 2012 but still a very deep contraction and despite that thanks to the diversification and at constant perimeters with other acquisitions, we would have seen a modest decline in our results. So we would have been in a safe zone anyway. Of course, we wouldn’t have the debt of the acquisitions.
[00:54:39]
[00:54:56]
[00:55:32]
[00:55:48]
So it was a very, very difficult situation. Italy was at the centre of the storm together with Spain and Greece. And first, the banks in the state were in trouble. And then the measures that were put in place in terms of, let’s say, reforms and fiscal discipline basically scare all of the Italian consumers who for like the next three to four years they stop buying cars, they stop buying houses. They were wondering if they would have a pension later in their life.
And so they were just not doing anything. And they demand it frozen. Maybe the reforms were not even too impactful. So it was just the thing that the country was in difficulty and they were to do serious reforms. That really scared everybody. And we don’t have anything like that. So today we have also reforms.
Now the reforms that Italy is doing are possibly similar to the ones of the time and they are now linked to resilience plans. So it’s like Italy is getting money and in exchange, Italy is doing reforms, which is a good deal for everybody, I think. And helps to give political support for the reforms. So we are doing things that are, I would say, as effective. But people are not concerned because it’s not the problem in Italy today.
Actually, there is low unemployment. Companies are doing well and so and so. In general, this is more like a recession that is not driven by a problem in the country, but it is kind of important. It has to do with the energy crisis and so on. And so people, of course, they’re spending less, they’re waiting to buy a house because interest rates are higher and maybe they cannot afford it. But there is not this element of fear that was present. But I think having been in the business for 20-plus years, the one that we have now is a serious recession or the behaviour that you would see in a recession for mortgages.
But it’s a normal situation, whereas the situation in 2012 in Italy was totally normal. It’s one of those things that you see once in 50 years. So I mean it’s not great what we are seeing for mortgages, for interest rates, and so on. But it’s going to pass and really doesn’t feel like what we had in 2012. Even just looking at the mortgage market.
Which past crisis does today resemble?
[00:59:38]
[00:59:54]
Especially in the BPO part. Some of our clients were affected. But in the overall mortgage market declined, but you could see it was temporary and things would go back to normal at a certain point. So and also previous recessions. But now I couldn’t tell the years we’re similar. So this a situation that you could see as a fluctuation and nobody in the country anywhere thinks that there is a risk for a permanent change, for a permanent impairment of the economy or whatever. You feel it’s like winter, but then the spring will come.
Whereas in 2012, at a certain time, the sensation that maybe the spring would not come. So the cause a permanent climate change. Here it’s like we are waiting for the spring to come back.
When does the group book revenue?
[01:01:50]
[01:02:11]
But in the great majority, there are some very small areas where we have to recognise with estimates but it’s normally we perform an activity and once we perform the activity we recognise our revenue. By the way, quite often we recognise the revenue when the activity is completed. So not halfway through. So I don’t think we have overall this issue. By the way, we have businesses where the activities are longer, but there are not so many.
So of course like mortgage underwriting that could take six months and there you have the issue of potentially recognising things that you have done that certain, but that you are not able to invoice, but that’s minor, but like in many other areas the activities from when we get the task to when we have performed it takes, say a month or so and there you easily recognise the revenue.
So I would say revenue recognition is again based on having performed activity and typically the revenue is recognised, then we issue an invoice right away and then the invoice is paid 60 days later. We have working capital because in many cases within the BPO division, we have an issue reconciling things with our clients.
So maybe the clients will pay us in 60 days, but before issuing the invoice we have to send them a report and they have to look at it and so on. And it takes a couple of months to do that. So typically, we have half of our receivables that are invoices to be issued. So we have performed the activity. We are reconciling so the invoice has not been issued yet and then there are another 60 days more or less that the invoices have been issued but not been paid yet.
But again we don’t have an issue of having significant revenues or receivables that come from estimates.
How does Marco Pescarmona judge business quality and capital allocation?
TL;DR: Brokering and BPO are about the same size. A 20% IRR is a good but aggressive number, and he sees the group as an industrial operator (2023).
Are both divisions equally good?
[01:05:23]
[01:05:45]
So it’s very nice. BPO is a business, the business that we have that is normally number one in all the important verticals in which we are present. So we have a strong position. It has the complexity that comes from needing not only technology because we use a lot of technology, but also a significant workforce.
So it’s a very strong business, it’s a market leader in verticals. These verticals are not so big. So these are issues that are quite defensible, I would say, but at the same time again we have the complexity of a large workforce and when you have capacity fluctuations, it’s more difficult to adjust. So these are the pluses and minuses of the two businesses.
And then again they’re about the same size. By the way, in the past, this may no longer be the case. In the past, we preferred BPO from the point of view of being able to deploy capital because we could make acquisitions there and we thought we could not do much in brokering. But this not no longer the case because now that we are international, we have possibly also opportunities for brokering to allocate capital.
For us, they’re like half of the business season. We like both, even if they have different characteristics and different investors highly value one part and or the other. It’s fairly like both at the same time.
Why do few players dominate?
[01:08:33]
[01:08:55]
And no, so I think they’re really nice for that reason. It’s also in that type of situation it’s more difficult to grow sometimes because one of the barriers to entry that we have in both cases is normally the fact that capital is not a strong driver of growth. So you commit more money to the brokering of the BPO division for organic growth.
Good Investing Plus
Meet the experienced investors
Plus is our application-based community of 200+ investors. Around half run or support a fund, or allocate capital.
- Online: idea exchanges and events every two weeks
- In person: gatherings in the US and Europe
- Omaha: our 150+ member conference in AGM week
And you don’t really know what to do with it. So you spend it, on brokering on advertising that has a very negative return because it’s all saturated or in BPO where do you spend it for? To develop IT systems maybe, but we are already doing it. It’s difficult to accelerate the growth with capital. This is the key characteristic of both situations and this is a key barrier too.
Is there a formula for capital allocation?
[01:10:35]
[01:11:11]
There will be flexibility in our decisions and we’ll consider things that are maybe not obvious. The things we could do anywhere from buying back shares to making acquisitions like the investment in money supermarkets was a capital allocation decision. In the end, it could be things like that. We and Alessandro are also owners of the business and we try to generate value for ourselves and all the other shareholders within everybody of course. In the same way, allocating capital in a very rational but at the same time sometimes creative way depending on the opportunities.
So we don’t have like a rule that says we want to make acquisitions first, but then we buy make or vice versa, et cetera. We see where things are and based on that we decide. So if we only had expensive acquisition opportunities, we would stop doing acquisitions. If the stock is super cheap, maybe we could become even more aggressive with the buybacks. Or if that is super expensive and we don’t know what to do with the money, we repay the debt. It really depends. The key point is this is done to the limit of our ability in a very rational way.
What else does spare capital go into?
[01:13:21]
[01:13:35]
But we did these investments to some extent working as an investor like doing the same things that people that come to our investor relations meetings. So they build models, and they try to figure out whether the management is reliable or not if they are honest people. So this was a bit outside of our standard, the expectations that people had for us running the company.
But we thought we had compelling opportunities and in the end and saying because in retrospect they would say, in the end, they generated very significant value and helped us to grow because these things have funded. Then we could fund the future industrial growth of the company. And this one thing.
The other thing is that in the past there was this opportunity, we had a different situation like this several times, but there was an opportunity in Italy to revalue intangible assets for tax reasons and it was a very, very nice law that they passed and basically you could pay like a substitute tax and revalue some of your intangibles and then amortise them for fiscal reasons. So that’s an investment in the end.
So you put up a certain amount of money and you get significantly more over five or 10 years. You can calculate the NPV of this and the internal rate of return and so on. The way we looked at it was as is very attractive capital allocation. By the way, this is a law that was very friendly to any company that had intangible assets, but many companies didn’t really realise that it was an opportunity or didn’t look at it the way with the same attention we put into it.
And it was capital allocation. Another example of capital allocation, which is just an opportunity, it’s not something we are currently doing. There are situations in which you could buy tax credits in Italy because they did some like state-sponsored property renovation schemes.
They generated a lot of tax credits for companies in the property sector, and these credits are transferable. And normally you have plenty of companies that have all these tax credits that are in excess of their tax capacity.
And so they might sell them. So you might be able to buy a relief on your future taxes at a discount. And so if discounts are at 5%, it’s probably not very interesting, but if it comes at 20% IRR, it’s very safe. This could be more compelling. So there are many things that could become available that have to do it. In the end, investments are about cash that could generate attractive cash flows given the price, et cetera and all these things are competing with each other.
Our focus is, of course, on developing our business in a way that people can understand that is predictable where we don’t buy a pizza chain, of course. So we do things that are predictable. But within our area of activity will be creative. With investments like money supermarkets that maybe are will be financial only or with things that have to do more with the debt management or asset management side of the company.
What return hurdle does he use?
[01:18:49]
[01:18:57]
So, I would say, sometimes we don’t get to the point of doing an expected IRR or having maybe a safe IRR and then taking the synergies or the external benefits as a plus. So that we don’t overpay on the explicit part. And then we have a part that is maybe not fully quantified that we get this bonus. But I think like 20% is a good number anyway. It’s an aggressive number. So private equity firms would normally aim for 20% more or less.
You are not always able to do that. I would say. Yeah, ballpark. I think the things we have done are in that area, but we could do things that are lower. Or where the explicit part is lower because when there is option value for instance, it’s very difficult to give a value to, I don’t know, the option the French market for insurance broker brokering will unlock it’s a lot.
You could do formulas like Black-Scholes or more sophisticated ones. It’s very theoretical, so you make sure that you are buying the company for a fair price and then you get the free option sometimes.
Is it still a two-division group?
[01:20:56]
[01:21:17]
Something that benefits from inflation, something that suffers from inflation, something that goes well when the economy is going well. Something that goes well when there is a natural catastrophe. So we have things that are very diversified. So the average cash flows will be, say, more stable. Then the way we look at it is still have two main businesses brokering and BPO. So for us, it’s still this the no part. We still see two main separate businesses that are generating cash flows.
[01:22:27]
[01:22:37]
So now we have a number of quality businesses individually. And to that, we have the quality of diversification. And that’s true for both divisions. By the way, diversification works both ways, so no single issue is going to kill you, but you’re always going to have issues in one place or another because you are playing many different games.
[01:23:30]
[01:23:42]
Are there more deals around today?
[01:24:22]
[01:24:46]
How does he see the group’s identity?
[01:25:17]
[01:25:29]
[01:26:10]
[01:26:15]
[01:26:19]
- Built an 8% stake in Moneysupermarket [00:18:23]
- A specialist owner with 20 years in the sector [00:28:21]
- Debt of about two times EBITDA in the banks’ view [00:47:15]