
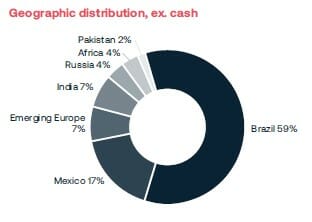
- David Nangle said VEF had 14 companies in the portfolio, six of them in Brazil (2021).
- Every investment must clear a 30% IRR hurdle, with a 10% currency headwind per market and year built in (2021).
- Over five years VEF delivered 27% returns on average per annum, he said (2021).
- Creditas made up 42% of VEF’s NAV (2021).
- VEF’s overall NAV was about $400 million (2021).
You are currently viewing a placeholder content from YouTube. To access the actual content, click the button below. Please note that doing so will share data with third-party providers.
More InformationVEF (VEFAB) · Creditas · Konfio
Guiabolso · Xerpa · Jumo · TransferGo · Juspay · FinanZero · REVO · Minu
VNV Global (VNV) · Tinkoff · iyzico · Square · Stripe · Adyen · Klarna · Tink · N26
What makes VEF the emerging market fintech investor?
TL;DR: VEF started five, six years ago with a pure focus on fintech in emerging markets. It held 14 companies, six of them in Brazil (2021).
Why “the” emerging market fintech investor?
[00:00:18] 

[00:00:40] 
So, it is not that other people locally, in Brazil, were not investing in some Brazilian fintech companies or some global venture capital funds did not find themselves in an Indian fintech company. But there was nobody who had dedicated themselves to this mandate totally and purely. So, I think we were very comfortable taking on the mantle of “the” emerging market fintech investor. Maybe it is because we are the only ones. So, it was “the” only one of one. But I think that is why, we were very happy in branding ourselves and calling ourselves that as opposed to there is 20 out there. And we felt we were the best, then shame on them.
Who competes with VEF?
[00:02:12]
[00:02:18]
So, not to move forward to other questions: But the beauty of venture capital versus investment banking, that I used to work in, is that it is not a zero-sum game. You can also invest more money in a company at an angel stage than a local seed firm in Brazil can invest. Then we can invest in partners of our own, and suddenly, six funds all benefit and win from the same growth trajectory of one asset. So, competition, collaboration, it is a lot more blurred in the world of venture capital versus the world of investment banking where it is a zero-sum, winner-takes-all, you-win-I-lose kind of thing.
What counts as fintech?
[00:03:43]
[00:03:52]
It can be very basic. It can be moving from a branch to a call center, which seems the old world, but just moving from that branch to the call center in some of the more frontier markets is taking that frontline out of the way. So, moving from paper to phone, now it is the phone to digital. It does not have to be the “tech tech” end of fintech. It can just be financial innovation and moving things forward. So, it is a broad-based area of fintech in terms of ideology, but also, it is broad-based in terms of segments. It is payments, credit, investments. It is a whole range.
Is there a playbook across countries?
[00:05:25]
So, you have limits in the financial sector. So, are you limiting yourself as an investor if you are going to focus on fintech as you bet on a certain nation? Is that right? Or is that idea wrong? What is your take?
[00:05:48]
I know you touched on the point around the regulator. What the regulator will let you do or not will not let you do, how enabling they are for fintech companies, how disabling they are for fintech companies. And all these aspects feed into how and where a fintech is at, in any given country who is driving that fintech evolution in some countries, I say it is the banks themselves, Russia. And in some countries, it was the new economy, giant social media, e-commerce- China. In some countries like Brazil, it is the new coming fintech companies. And in some countries like India, it is the government. In general, you never get innovation out of a government, but we did. And they all are the ones which are moving financial innovation in fintech forward.
And it just makes it so interesting that we do not have a color-in by the numbers playbook for each country as we go. Each country is different based on all the moving parts that feed into how we think about the opportunity in a country’s size and scale, what space we want to be in small business, consumer payments, credit, and when we want to be in it. So, it is fascinating as a top-down ideology, but the bottom up from each country is totally different.
Where is the portfolio concentrated?
[00:07:56]
[00:08:04]
When should companies expand?
[00:08:53]
[00:09:04]
But once again, it is of the base of strong success in its core market. We hate people running off to more markets when they have not succeeded in their own market. But Creditas to us is very front and center in that. Konfio can do something similar in Mexico. But then we have a couple of companies that are multi-country players and that is more like TransferGo in the remittance space. So, it feeds its model into many countries like Jumo, which is in mobile financial services and banking as a service in Africa. They are present in many countries. And then there is Revo that is taking the “Afterpay” business out of Russia, while still being in Russia, but they go from Russia into other markets of Eastern Europe. So, there are a few multi-country plays. But the singular country plays are the ones that we love because of their focus
Why does the decline of cash matter?
[00:10:26]
[00:10:32]
Good Investing Plus
Meet the experienced investors
Plus is our application-based community of 200+ investors. Around half run or support a fund, or allocate capital.
- Online: idea exchanges and events every two weeks
- In person: gatherings in the US and Europe
- Omaha: our 150+ member conference in AGM week
[00:10:39]
What is your take on cash? Is it kind of your enemy, if you are thinking about cash societies like Mexico, where still a lot of the transfers are done by cash? What is your relationship to cash as a fintech investor?
[00:10:57]
So, I think the war on cash is a very positive one both from a government point of view and from a company point of view. And the trend is clear global, that cash is a dwindling proportion of overall savings, spend and use in society. And that is a net positive for fintech. So, I did not, we are quite comfortable with the trend. It is positive for what we do. I think with COVID it kind of got a step-change in terms of pace. As some countries like India were a bit more dramatic and they had a demonetization push. So, you get these kinds of step changes, but the gradual move is towards a cashless world.
[00:12:22]
[00:12:25]
How does VEF deal with currencies and difficult markets?
TL;DR: VEF uses a 30% IRR hurdle and builds in a 10% currency headwind per year. China is a market where it would not know where to start (2021).
How does VEF treat currency risk?
[00:12:28]
[00:12:59]
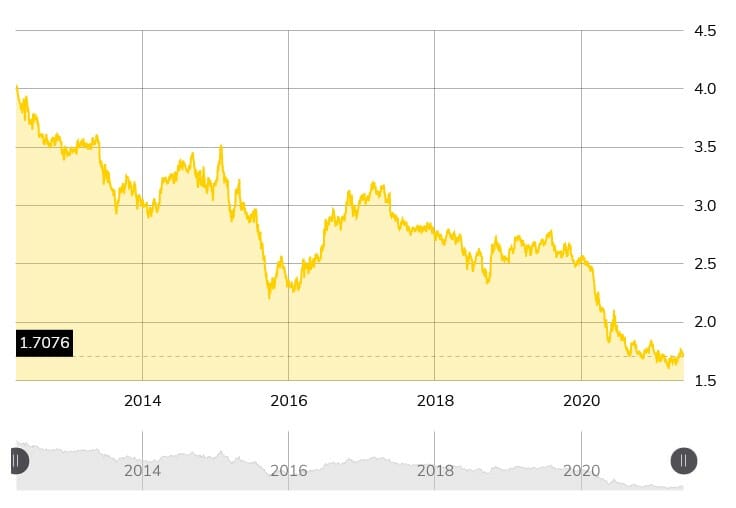
So, we accept the currency headwind. I will not say we welcome it, but it is a fact of investing in these economies and what it does do: It keeps a lot of the competition away so we can find the best assets at the best prices. We can enjoy that structural growth story. Albeit we need to factor in those currency headwinds. Now, if you look at Turkey, which is a classic example, and you know, you bring up a chart comparing the Turkish Lira versus US Dollar over the last 10 years, and it is horrific. We made a 60% IRR on our iyzico investments, over a two-and-a-half-year period. And we invested when the tanks were on the streets. We invested whether they were, it was volatile, but it was a company that was doubling and tripling year on year. So that is one of the headwinds or cons and in our investment case. But once we are investing in the right companies, we tend to outgrow those headwinds.
Which hurdle does VEF use?
[00:14:38]
[00:14:57]
Why avoid Argentina?
[00:15:37]
[00:15:57]
Argentina, I am a big fan of Argentina as a country. But as an investment destination, it is a hard country, almost from a macro level, more so than a micro level. It is a country that has been in a difficult leadership macro place for quite a long time, but it is a country that I have been to, and it is phenomenal as a country both the Capital, the countryside, and the coastline. So, I would spend time there. I do not know if I would invest there as an emerging market and that is for me from a finance and family point of view.
Personally though, I like a bit of adventure. So, there are many emerging markets that I would travel to that I would not invest in, be that Belarus, Venezuela. But I would not bring the family and I would not bring the best dollars there.
Why not China?
[00:17:10]
[00:17:21]
What does VEF look for first?
[00:17:50]
[00:18:08]
People, people around the people. And then even after that, then the “legal” kick in. We have in-house counsel and out-house counsel, and a lot of these companies’ jurisdictions are outside their countries that are in Delaware or Cayman’s or Singapore, and then the “legal” kick in to save us from ourselves if everything goes wrong. But a lot of this is around the people. And then once we are in, we are board members. So, we are active investors. We are on the board of 12 out of 14 companies. As a team we are getting, sometimes daily updates, weekly updates, monthly updates. We are on quarterly board calls. There used to be board visits. And, but obviously, COVID put a few headwinds on our travel in this period. But we get back to that and get back on the ground. And we have got a lot of venture capital partners as well, who are co-board members. So, a lot of work goes in that.
How does a lean team find and hold investments?
TL;DR: Eight people, more than 100 companies looked at so far in 2021 and one or two new investments a year. Tinkoff was held from 2005 to 2019.
How lean is the team?
[00:19:50]
[00:20:07]
How selective is VEF?
[00:20:51]
[00:20:58]
So, I think the pipeline is not our problem in terms of quantum, but the quality is. And we have a high bar. We look for a bunch of things in any investments and, we have not found an investment this year that we have done yet. We have done two investments this year, but they were from last year in terms of closing this year. So, we tend to do one, maybe two new investments a year. We are in no rush. We just sit back. We wait for the buses, they come, we watch them go by and when we find one, we like we try and jump on.
What kind of VC is VEF?
[00:22:20]
[00:22:36]
Why permanent capital?
[00:23:37]
[00:23:40]
So, in Turkey, we were in and out of a company in two and a half years. We did not plan to b. We have got an offer we could not refuse. So, we did not. That was a good return. But looking at Tinkoff in our portfolio in the past, that is one that the Vostok group invested in back in 2005, and we only exited the final piece out in 2019. I look at something like Creditas or Konfio in our portfolio today. They are companies that I can see us being in for 10, 15, 20 years given the space that they are in and the scale of the opportunity, their track record of delivery. That kind of the hundred percent plus growth may become 50% may become 30%, but we want to be there to enjoy that journey.
How does VEF win deals?
[00:25:00]
[00:25:06]
I also think it is good from a professional process point of view is to have some exits I will not say investing is easy, but investing is easier than getting money back. So, to keep a certain level of exits going as you go through the cycle is a healthy discipline to show the cash comes in as well as cash going out. And investors like to see that. But it is fundamental support of founders with founders on their journey once they are succeeding and I am looking to exit with them at the right time, IPO, or M&A.
Where does VEF want to improve?
[00:26:19]
[00:26:29]
So, we have gotten better in absolutely everything. But for the most part, it is really on the investment side: Finding investments, the diligence in the investments working with our investments, growing up with our investments in terms of what works, what does not work, mistakes made, battle scars, which are the best ways of learning. Unfortunately, it is with capital depreciation when you make a mistake. But overall, our mistakes have been small, so far, and our wins have been big. So, net-net it has been a positive education journey as opposed to one of those investment education journeys, which ends up with a zero. And we all learned a lot from that, but we got a return. I think over the last five years we have been delivering 27% returns on average per annum while getting an education.
But where can we get better? I think we can still get better at working with our companies and help them. It is a real goal of ours to be the number one investor for each of our companies. And that just comes with time and experience, and you know, I think on the investment side, you can always get better: better at being quicker with our pipeline, more efficient, and finding the assets that we want.
What drives David Nangle and how does VEF relate to VNV?
TL;DR: He joined from investment banking after the Tinkoff exit. VEF and VNV split fintech and marketplaces into two companies (2021).
Where did his career start?
[00:28:18]
[00:28:28]
So, it is kind of like my ideology moving out of banking, into running a fund of some kinds that are classic venture capital or listed investment company to invest in future Tinkoffs cross-referenced with Per Brilioth on his timing, moving Vostok Nafta away from what was marketplaces on one side and some fintech on the other. So, the conversations became organic as opposed to Per approaching me and saying: “Come on board and do this” or me approaching Per and I should come on board and do that.
We just kind of got together and kept on talking through the Tinkoff process, through the exit, talking to some of the investors behind Vostok. And almost regardless, he came to the point where he was saying, I should come on board. We should split marketplaces on one side. Fintech on the other. We should build two separate entities. And we should raise capital around the fintech entity. That is a rebrand, also VEF and VNV. And off we go. So, easier said than done, but an amazing time opportunity meeting of minds in hindsight as it was a great thing to do at a great time. And I say that because we succeeded. Clearly, success makes you feel happy in hindsight.
What is he building?
[00:30:28]
[00:30:39]
We need to make money for our shareholders and deliver a great return. All with a growing ESG overlay and because the impact of what our companies do is very important as well. So, I think these are the motivations. It is about creating something. We are investing in companies who are themselves building businesses. While we ourselves are a startup building a business. We are a six-year startup. We have got eight people. We started with sub $100 million of NAV and market cap. And now we are $400 million of NAV and market cap. We had one investment at the start. We have had 16. We have got two exits. We are building our own startup story and we’ve kind of gone from an early seed stage series to series B or C stage. But there is a lot more to go.
Will he retire?
[00:32:09]
[00:32:17]
How does VEF relate to VNV?
[00:32:49]
[00:33:00]
What does VEF copy from VNV?
[00:33:47]
[00:33:51]
Dare to be different: Look, I think, individually where we are different people running different companies. So, I think they have gone to developed markets. We are staying pure in emerging markets. I do not like developed markets. Developed markets are too stale, too boring, too competitive. I have no interest in France or Germany, no offense, or the USA. It is all about Brazil, Pakistan, Egypt, Russia for us and at VEF.

So, is that different? That is just our core focus. And that is one thing. Maybe on the team front, we have a bit deeper of a team, even though both teams are small and lean, I think ours is less lean. Is that daring to be different? Maybe a slight difference in ideology.
How are the team and capital aligned with shareholders?
TL;DR: About half of his net asset value is in VEF. Buybacks and new deals must both clear a 30% IRR (2021).
How is competition changing?
[00:34:53]
[00:35:04]
The beauty of what we do is. When Brazil gets hot, we can invest in Mexico. When Mexico’ is hot, we can invest in Egypt. There is always a place that is less hot if the valuation is a key aspect of what you do. But also, we are quite comfortable in our own skin in terms of what we do and our dedication to emerging markets and fintech. And it generally helps us get into the right investment opportunities, even if there is a lot of competition out there, which is turning up for the first time in these markets.
How much of his wealth is in VEF?
[00:36:21]
[00:36:32]
I have got no other key investments. My only investment, my only focus is the main job. That is VEF. And I do think about VEF from a personal financial point of view, but that is not my prime. I think that is the output. And based on the function of delivering a great company and a great product and great shareholder value, then I will wake up one day and it will be worth a lot.
How is the team paid?
[00:37:19]
[00:37:28]
When do buybacks make sense?
[00:38:00]
[00:38:03]
So, we haven’t had to do anything extensive on the buybacks to date because the share price has been in a good place, especially more lately in a good place and close to NAV, but going forward, if there was a massive dislocation in our share price and we were sitting on cash, the best thing we could do from a value-add for shareholders point of view is buy back our shares. So, there is a place for it is part of our investment thesis, but we have not had the opportunity to do something aggressive on that front yet.
How does VEF build its portfolio and value its companies?
TL;DR: VEF seeks concentration: Creditas was 42% of NAV. Companies are marked to the last round for up to 12 months (2021).
Does VEF diversify its winners?
[00:38:55]

[00:39:24]
So, Creditas today is 42% of our NAV. And we are very happy for that to be 50%, 60%, 70%. Then we move to exit. We take capital off the table at some point. And we do it all again, in theory.
So, are we looking at a kind of portfolio theory or portfolio spread across different countries across different stages? No, we are not. We are looking for on a micro level, the best fintech company opportunities. We get them into the portfolio. When they are performing, we look to concentrate the hell out of them. And as we have in Creditas and that is, that is good news for us. So, that is how we think about things.
So, today we are Brazil heavy, and we are Creditas heavy, or LATAM heavy. Three, four years ago we were Russia heavy. Now in five years’ time, we might be India heavy. And that is geographic. And that might be company-based, but you know, we are quite open to that. And that is, that is the way we think about it.
Which problems do the fintechs solve?
[00:40:54]
[00:41:00]
It can be a 100%. So, a lot of our companies are providing a) a better product, b) at a better price, which is not hard given the incumbents and their cartel. Also, for user experience, we see a much better user experience across most products and most of our markets. Then there is the aspect of the un-banked and under-banked. Jumo is providing financial services to people for the first time in Africa. So, working with the MNOs and mobile operators and the banks on the other side. They are delivering a financial product to the owner of the banks.
And so is Konfio in Mexico, where small businesses are just under looked by the big bank. So, when it is a first product or a need for the product in wide-open spaces. What is a better user experience? Whether it is a better price point? We are talking about all those problems with different companies in different markets.
How far does copy-paste go?
[00:42:11]
[00:42:18]
So, online payments or small business lending, some like Square or Stripe exist in the US or in Europe, I guess, N26 or Tink, or Klarna, these models pop up. They tend to compliment in Brazil or Turkey, more developed emerging with quite decent banking systems.
We did our iyzico in Turkey in the past online payments processing. That was very much the Stripe and Adyen model for Turkey. A bunch of Germanic Turks came back from places like Hamburg and Nurnberg moved to Istanbul, they are ex-Klarna, ex-PayPal, and they built the model. They are pretty much copying the Stripe or the Adyen model, but for a Turkish market.
So, I think in those markets, which are developed emerging: There’s a lot of copy-paste, replicated execution with some local flavor. And for us, when you get the right founders doing that, it is great. There is a good playbook there, and it is probably the quickest way we get the best return on capital.
Other markets and other models are very fit for purpose in the frontiers where it is very early stage, very cash dependent. And it is copy-paste, replicate and execute. So, Jumo is a totally unique model for a unique space in Africa, versus other things like Creditas in Brazil, which is, very similar to what happens at Carvana or Rocket companies in the US or Konfio in Mexico, which is building like the Square Capital of Mexico. So, yeah, there are a lot of different examples there.
Which companies are recovering?
[00:44:02]


[00:44:49]
We found that over a two to three years period. So, we marked that down aggressively as that model effectively was not working. And, but what we have found is that open banking is a big thing globally in Europe and now in Brazil. The regulators are forcing it and our technology is well placed for that. In the B2B open banking space, Guiabolso is front and center and you can almost see a second coming or a second wave or growth trajectory in that. But I think what that NAV mark shows to our auditors and to our investors is, we are quite quick to mark things down for conservatism, if something is not working, as opposed to keeping valuations where there may be not justified at that point.
Good Investing Plus
Meet the experienced investors
Plus is our application-based community of 200+ investors. Around half run or support a fund, or allocate capital.
- Online: idea exchanges and events every two weeks
- In person: gatherings in the US and Europe
- Omaha: our 150+ member conference in AGM week
I think Xerpa is one where it is in the salary advanced space. So, it is giving you employees access to your earned salary in advance of the end of the monthly payroll. And we invested in that in Brazil just before COVID. And it was just launching the product. So, we’ve kind of had a standstill, as Brazil has been in a standstill and human resource departments have been in a standstill for that window. So, it kind of took us a year delay. So, through COVID and with the currency and with Brazil, we just got more conservative because the model had taken a long time to really pick up and grow. And it is only starting now. So, it is kind of like we lost a year, but that brought in conservatism in valuation.
And the final one Jumo is one where: That’s really starting to hum now. It is really, the partners are starting to kick in. This is Africa, there is an element of credit. So, during COVID, we got very conservative, just in case, on that model. And, but now we are starting to come out at the other side. And I think you have seen the NAV marks of Jumo in the last quarter, but things are starting to come back in the right direction. And that is a function of how well the business is doing.
How does VEF value its holdings?
[00:47:14]
[00:47:29]
And if those companies are not performing versus when we initially invested, according to that plan, we happily mark them down to a new valuation based on how the markets are doing, how their peers are doing, multiples of the peers, how the currency is doing. As we have seen, the currencies can move against.
So, in many cases, we are moving things up in valuation over time. In some cases, we move things down to move back up. So, it is, it is kind of an iterative quarterly process, but it is very formal, very mathematical done by orders. And you know, we are quite quick to mark down when we feel a bit more conservative about them, as much as we are quick to move them up when they are on fire in a good way.
What counts for the NAV?
[00:48:33]
[00:48:41]
But the most important point for any day when we wake up is what we have in our NAV today. And that is reflected in our overall NAV, which is about $400 million, and reflected in how the market sees us on our market cap. So, we always ask ourselves from here today: How will this company do? Whenever companies are looking for capital: We ask them, as of this point, it is not historically, should we give them more capital for the buy they can create from here going forward?
So, all three companies are in a much more stable/positive footing in their journeys, versus when we took down their NAV marks. And a lot of that NAV mark movements was during COVID, conservatism, and they are starting to come out of that.
Where does the team spend time?
[00:49:37]
[00:49:50]
We have a portfolio of companies, who have got a team of eight different people, aligned with each one and we work with these companies to help them out in any way we can, whether it is raising capital, modeling, decision-making, and we look to help them win at any point in their cycle. So, we do maybe on average, tend to spend more time with the bigger companies of our NAV because they will have more impact.
So, the more positive impact we can have on Creditas and a Konfio the more positive impact it will have on our overall NAV and hence our share price and for shareholders. But that is only marginal. And what we tend to find is that the bigger companies, because they have got to a stage where they are big, more professional, deeper, they maybe need less of our time for some of the smaller companies that are only small parts of NAV more of our time. So, it tends to evolve.
What is the case for Creditas and Konfio?
TL;DR: Creditas was valued at $1.7 billion in its last round. Konfio was worth about $300 million in its last round (2021).
What does Creditas do?
[00:50:51]
[00:51:11]
The founder is a person called Sergio Furio. He is Spanish from Valencia, but he moved to Brazil with his wife at the time. He is ex BCG. So, he is a consultant, super logical, very energy driven, very methodical in his thinking. He has got an excellent team around them and some of the best investors in the region. And more importantly, he is playing into a scale opportunity place, which is secured lending in Brazil.
So, this is lending to people by using collateral against their home or against their car or against their payroll. So, it is lower risk lending in its nature. But what Brazil has is a very big unsecured loan book at horrific rates. So, he is lending to people at much lower rates, bigger amounts, better economics and safer effectively.
So, instead of you going out and borrowing off somebody for 50% as a loan rate, you can borrow up Creditas and get for 10% if you put your home in a Brazil context. So, it is a good ethical ESG overlay what they do. It is a scale space. It is $500 billion existing unsecured credit in Brazil today. And that needs to be replaced by more longer-term secured credit over time.
The Creditas loan book is only about 300 $, 400 $ million today. So, the thing where they can grow 2-3x a year for the next 10 years is very realistic, given their size and shape. Also, they are doing a lot more around the collateral of home, auto, and payroll, where they are getting deeper into these three ecosystems and providing more financial services around these kinds of products suite.
So, they were lending against cars. Now they are lending to buy a car. Now to do insurance for cars, you need a buyer buying and selling cars. So, there is a whole ecosystem going in around the car. And they are doing something similar at home. They are doing something like payroll. And as we talked about earlier, the moving from Brazil into Mexico. So, from one scale market into another. It is a company that was valued at $1.7 billion in its last investment round in Q4. It is on a path towards IPO, which we with the exits and transparency and pricing. It may raise more capital before it gets to IPO. We will see. But this is a company where we can see the predictability of compounding of value from a bigger base is very real. And that is something that gets us excited.
So, it is not always companies, which. “What is it yet? We do not know.”, or “How will it monetize?” or “What happens next year?” There is a real degree of forecast ability around the path that they are on, with some risks, always. But that is what excites us a lot, and we can see the value in this compounding. This is a 10 $ billion. It could be a 100 $ company in the making because they are a part of the future of finance in Brazil. They are on a very strong path towards it.
What is the biggest risk for Creditas?
[00:54:11]
[00:54:12]
Fintech exists because banks are just, well they are old world. They were asleep at the wheel, and they allowed for innovation to come in around them. So, I think this is an area where the banks have maybe some competitive advantages around the cost of capital, and they have a lot of the customer bases that they’re lending to currently in an unsecured format.
So, the banks must undercut their own revenue to give their own customers a better product at a better price point. But it is possible they could do that. So, I think the biggest risk for Creditas is around the competitive aspect, but we have not seen anything too much there. And it is such a big space that there is room for more.
What happens at the IPO?
[00:55:05]
[00:55:15]
We could very easily not sell a share in the IPO and hold on for another five years. Or we could sell everything in the IPO because we think it has gone far enough or it was an IPO that everybody wants a piece of, and its price way too high. So, we would have to make decisions at the time. Most realistically is probably a case of taking X off the table in the IPO and holding Y for the journey thereafter. But there is plenty of time to get into that before we get there. I think in the meantime, what we want to see is: This company continuing to compound up in value. Our shareholders are getting closer to it, understanding it, that it is being reflected in our share price and everybody is happy.
What does Konfio do?
[00:56:25]
[00:56:30]
And we found Konfio, which is focusing on the credit space, small business credit. But they have an aspiration of becoming like what Square is in America or TAG and Stone are in Brazil, which is a small business financial services ecosystem. So, for small businesses, you do their payments, you do their credit, and you do their management information systems or accounting and processing. And that is the path that they are on. So, credits first, but they have also now moved into payments, inorganic as well as organic, and same with ERP.
So, this is a company which in the last round was worth about 300 $ million. They are probably having to raise more money this year. And this is a company that will support them in that journey. But this is one that can be the dominant financial services play for small businesses in Mexico and. And even across the world, Tilman, you find the small businesses, I guess Germany is an exception because small businesses are everything in Germany and the banks are built to support small businesses. But you know, elsewhere in the world, small businesses are one of the biggest unserved parts of financial services. Everybody focuses on consumers or big corporations, but small businesses do not get a lot of love. So that is a big opportunity.
Where does VEF see the next opportunities?
TL;DR: Pakistan and Egypt get a lot of time. In India, 80 to 90% of usage is mobile-first (2021).
Where do fintechs move next?
[00:58:22]
[00:58:40]
At the same time, we are seeing a lot of these new fintech companies moving into the real economy. So, you started off as a digital bank, but also suddenly you are doing ticketing. And you are doing E-commerce or marketplace on top. You might be doing auto lending, but suddenly you are doing buying and selling cars and maybe producing cars. So, financial services are moving into the real world while the real world’s moving into financial services. So, I can see that through a lot of our companies, especially the ones that have a lot of customers, have a lot of brand loyalty and capital, moving beyond core financial services into other areas. Specifically, that can be in areas like health or mobility or education around which people are borrowing for payments in.
Geographically, I think there are lots of opportunities, especially Creditas and Konfio. They can dominate Latin America for their product suite. And then going beyond that is probably a push too far, but you never know, REVO is across Eastern Europe now, and Jumo in Africa could easily be across Southeast Asia, which is a very similar market to the subcontinent and Southeast Asia. So, geographic expansion is a lot easier than product expansion. But that product rollouts beyond the core that they are all delivering on, can be a financial service, which is easy to go from payments to credit to investments to insurance. Outside of financial services, that is starting to happen, which is probably one of the more interesting dynamics that we are seeing.
Why is change slower in developed markets?
[01:00:27]
[01:00:45]
So, I guess if you are going to Sudan, or you going to Bangladesh or pick a market. And you are looking at the future of funds, you do not have to go through all the historic chapters, and you can go straight to the best in class. You mentioned China. China has a great track record of data just moving straight to digital because it was driven by the new economy companies.
So, I think there’s learning there, but I think that the unfortunate part about the developed markets is: We have a history. You do not get rid of those things gradually and then innovators come through. And they take the top of the ends of the pyramid, and it comes rolled through to everybody else. So, I do not know if we could do take the benefits of emerging markets to the developed world in such a dramatic sense. Gradually, but not as dramatic as what happens in China, where you go from cash over here to a hundred percent digital over there.
Which new markets is VEF looking at?
[01:02:24]
[01:02:26]
So, we are looking at them, with fintech eyes, even though they are not a core fintech companies. So, I guess what, you could see something popping up in our portfolio in health or education. And you might go, what the hell is that? But there is an aspect of fintech and a growing aspect of fintech in that. So, I guess that is probably the most interesting one. And then do the insurance parts where classic fintech innovation is being quicker or deeper than what has happened on the insurance side. The insurance opportunity is as big. So, we are looking at the innovation and that is probably the next wave of investment source to do, as that progresses.
What is the priority?
[01:03:48]
[01:04:01]
That said, if I look through our portfolio and some of the names that exist across different areas. Like there are more recent ones in India. India, such a scale market. But it is Juspay and mobile payments or rupee gold back lending. No matter how you look at them, they are only getting started even though they are a company worth north of a 100 $ million dollars. There is so much scale in that market and so much wealth creation on an individual and collective basis in that market. From a macro perspective, you cannot help, but be excited by the Indian opportunities in the portfolio.
But if it went back down to the smaller end of the scale, and what is interesting. Which one would I pick? I guess I am looking at a specific FinanZero in Brazil, which is very early. It is a marketplace for lending. But lending is just booming in Brazil, and they are just sitting in the middle. They are not taking it onto the balance sheet. They are just connecting lenders to borrowers like the smarter model in Europe or Lendo in Scandinavia. Copy-paste, replicate: We talked about this. Great founders executing and that they just can keep on doubling and doubling. Without taking any balance sheet risks, just being part of the market trends. So, that is quite nice to see play out.
[01:05:38]
How early is emerging market fintech?
[01:06:30]
[01:06:35]
Two it is an element of the space that we are in, the markets, emerging markets, and fintech we are only getting started in terms of, five years in, a lot of value created, but you know, there is a long-term journey here and we are very comfortable in our own skin. And there will be cycles in this and what we do. These markets blow hot and cold. But we are doing it for the next 5, 10, 15, 20 years. So, we are making decisions today, which are very much focused on that long-term horizon, as opposed to maybe some of the classic VCs, which raise a fund to close a fund, raise another fund to close a fund. Ours is evergreen and it is important that we think long-term.
What enables it all?
[01:07:31]
[01:07:47]
How mobile is the business?
[01:08:55]
[01:09:03]
[01:09:35]
[01:09:45]
[01:10:19]
[01:10:23]
[01:10:28]
[01:10:29]
- 14 portfolio companies at the time, six of them in Brazil [00:08:04]
- Uses a 30% IRR hurdle for every investment [00:14:57]
- CEO has about half of his net asset value in VEF [00:36:32]